Hollywood has lost some of its automatic advantage
The European Audiovisual Observatory estimates that North American films accounted for roughly 52% of worldwide admissions in 2025. In 2019, that figure was 63%. Asian films moved in the opposite direction, climbing from 27% to 36% over the same period.
Asia itself accounted for 54% of global theatrical admissions in 2025. More strikingly, domestic cinema dominated several huge Asian markets: roughly 90% in India, 75.6% of box-office revenue in Japan and around three quarters of the Chinese market.
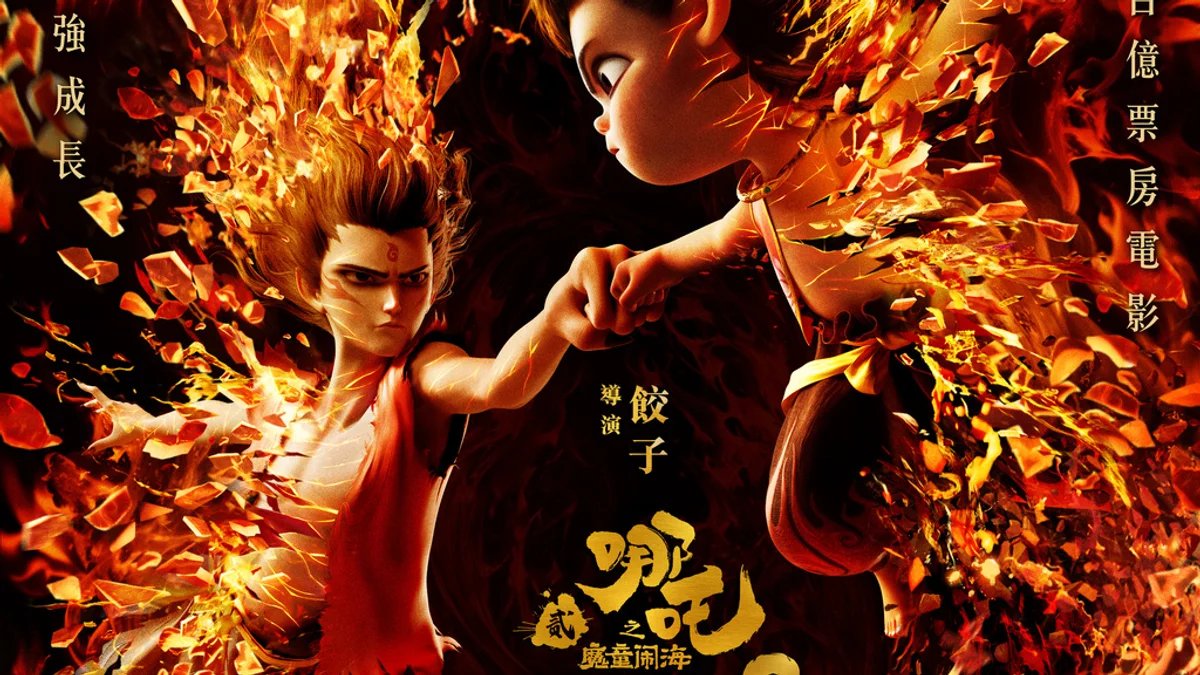
Ne Zha 2 turned that shift into an impossible-to-miss headline. The Chinese animated blockbuster became the first film from a non-US studio to top the Observatory's annual worldwide ranking, at an estimated €1.8 billion. It did so while leaning heavily into Chinese mythology rather than sanding away its cultural identity to resemble a conventional American export.
Japan has built an unusually powerful home advantage
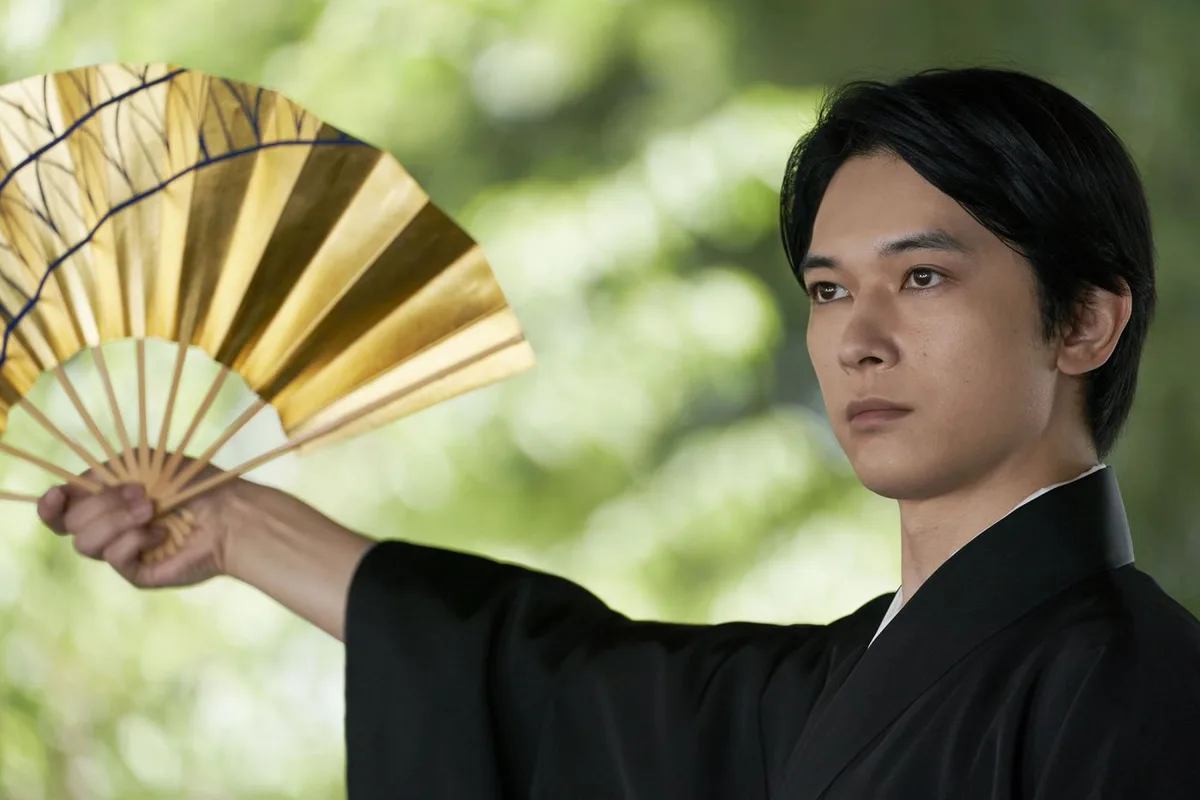
Japan recorded 188.8 million admissions in 2025. Total box office reached ¥274.45 billion, up 32.6% year on year, according to the Motion Picture Producers Association of Japan. Domestic films captured 75.6% of that revenue.
Demon Slayer: Infinity Castle was the year's biggest Japanese film, followed by Kokuho and Detective Conan: One-Eyed Flashback. That top three is revealing. Anime remains a formidable commercial engine, but Kokuho — a nearly three-hour live-action drama centered on kabuki — became a major cultural and theatrical event as well.
Japan's advantage is not simply that it owns popular franchises. Manga, anime, games, television and cinema feed one another inside an ecosystem where a property can become enormously commercial without first being redesigned as a generic international product. When something such as Demon Slayer then breaks through overseas, the export comes after the domestic cultural connection rather than replacing it.
South Korea is recovering, although one giant hit can distort the picture
South Korea's first half of 2026 looked dramatically healthier than the same period a year earlier. The Korean Film Council reported KRW 579 billion in theatrical revenue and 57.05 million admissions, increases of 41.9% and 34.2% respectively.
Korean films generated KRW 370.2 billion, up 81.7%. Their first-half revenue recovered to 94.2% of the 2017-2019 pre-pandemic average.
There is an important asterisk. The King's Warden became an extraordinary domestic phenomenon, eventually passing 16.9 million admissions and setting a Korean box-office revenue record. One movie therefore carried an unusually large part of the recovery. South Korean cinema looks far stronger than it did a year ago, but the industry still needs a dependable pipeline rather than a succession of rescue missions by exceptional hits.
India makes the Hollywood comparison look strangely narrow
India is not one film industry patiently waiting to challenge America. Hindi, Telugu, Tamil, Malayalam, Kannada, Marathi and other industries overlap, compete and exchange stars, stories and dubbed releases across an enormous domestic market.
According to Ormax Media, films released during the first six months of 2026 generated ₹63.98 billion in India, 10% more than during the equivalent period in 2025. Admissions rose 5% to 378 million, reversing three years of decline or stagnation in footfall.
International films can still become major Indian hits, and their share increased during parts of 2026. But domestic cinema accounted for about 90% of India's box office in 2025. Hollywood is an important participant in that market, not its default center.
Where Asian cinema currently has the edge
If the test is the ability to make local audiences choose domestic productions over American imports, several Asian industries are currently in an exceptionally strong position. They also have considerable freedom over what a blockbuster can look like. Chinese mythology can support an animation on an enormous scale. A kabuki drama can become one of Japan's biggest releases. Indian hits can move across linguistic markets rather than relying on a single national production center.
That cultural specificity matters. Hollywood spent decades building films for maximum international legibility. Asian industries increasingly demonstrate another route: become indispensable at home first, then export the films that prove capable of crossing borders.
There is no single Asian success story, though. China's box office dropped 40.6% year on year in the first half of 2026 to RMB 17.35 billion, according to Maoyan figures reported by Screen. The comparison was particularly brutal after an extraordinary 2025, but it exposed how dependent even a gigantic market can become on the supply of major local releases.
South Korea has its own production and theatrical pressures. India remains dramatically under-screened relative to its population. And Japanese anime travels internationally much more reliably than most Asian live-action cinema. Domestic dominance and global dominance are not the same achievement.
Hollywood had a very good summer
Any obituary for Hollywood would also have terrible timing. From May through August 2026, the North American summer box office generated roughly $4.6 billion, up about 26% from the previous summer, according to figures reported by Reuters in early September. It was Hollywood's strongest summer since the pandemic.
American studios still possess an extraordinary global distribution network and remain particularly effective at turning premium formats, recognizable franchises and major releases into worldwide events. Hollywood films still represent the largest single share of global admissions.
What has weakened is the assumption that an American blockbuster automatically occupies the center of every important market. The global share for North American films falling from about 63% of admissions in 2019 to 52% in 2025 is substantial even though 52% remains dominant.
The more interesting contest is between two different kinds of strength
Hollywood remains exceptionally good at designing, financing, marketing and distributing movies intended to work across dozens of countries at once. The strongest Asian industries increasingly excel at something different: producing films that their domestic audiences consider more relevant than Hollywood's alternatives.
Japan can then export selected franchises through a mature anime ecosystem. China is large enough for a truly exceptional domestic hit to alter the worldwide chart. India can support enormous productions across several language industries. South Korea has already shown that films and series in Korean can become international cultural events without abandoning the language that produced them.
So the current advantage depends on what is being measured. Hollywood still has the broader and more repeatable worldwide machine. Asian cinema currently has remarkable local strength, growing global weight and, in several markets, a closer relationship with audiences than imported American films can claim. In Japan, domestic films took 75.6% of 2025 box-office revenue. In India, local cinema held roughly 90% of the market. In South Korea, Korean productions occupied all three top positions in the first half of 2026.